Yingli Wang
Academic homepage

Yingli
Wang

Postdoctoral Fellow at the School of Mathematical Sciences, Fudan University. I work in applied probability, studying stochastic processes, Monte Carlo methods, and problems in financial mathematics.
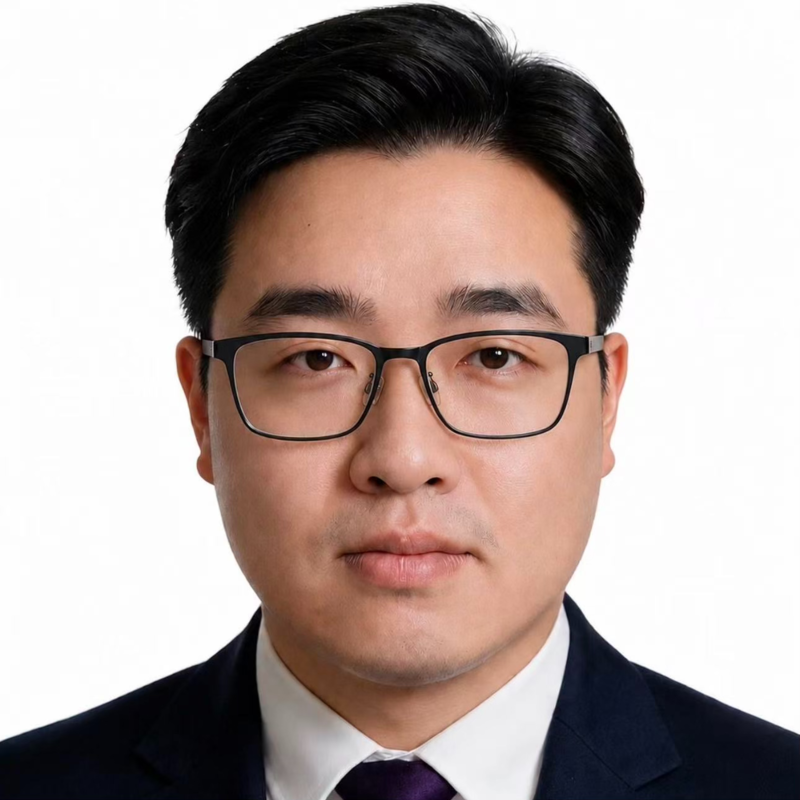
Portrait of Yingli Wang School of Mathematical Sciences · Fudan University
Applied probabilityShanghai, China
Current positionFudan University · Shanghai
Research homeApplied Probability
Academic backgroundPh.D., Shanghai University of Finance and Economics
01 / Research

Questions at the meeting point of probability and computation.

My work connects stochastic models with their scaling limits, numerical methods, and applications in quantitative finance.

01

Stochastic processes

Hawkes processes, heavy-tailed systems, limit theorems, and the emergence of rough dynamics.

02

Monte Carlo methods

Sampling algorithms, high-resolution dynamics, and their behavior in challenging probability landscapes.

03

Financial mathematics

Rough volatility models, scaling limits, hedging, and option pricing.

02 / Selected work

Publications & preprints

A selection of recent work. Author order and contribution notes follow the publication record.

2026

Accelerating constrained sampling: A large deviations approach

Wang, Y., Tu, C., Wang, X., and Zhu, L. · Journal of Machine Learning Research, 27(118):1–61

2026

Scaling limit of heavy-tailed nearly unstable cumulative INAR(∞) processes and rough fractional diffusions

Cai, C., He, P., Wang, Q., and Wang, Y. · Methodology and Computing in Applied Probability, 28(13)

2026

Precise deviations for discrete marked Hawkes processes

Wang, Y. and He, P. · Communications in Statistics—Theory and Methods, 55(15):5040–5061

2025

Rough Heston model as the scaling limit of bivariate cumulative heavy-tailed INAR processes: Weak-error bounds and option pricing

Wang, Y., Cui, Z., and Zhu, L. · SIAM Journal on Financial Mathematics

2026

A Hawkes microfoundation for multitype inverse Gaussian subordinators

Wang, Y., Xu, W., and Zhu, L. · Preprint

2026

Global convergence of third-order Langevin dynamics for non-convex optimization via simulated annealing

Wang, Y. and Zhu, L. · Preprint

2026

Variance-optimal hedging in the rough Hawkes–Heston model

Wang, Y. and Wang, X. · Preprint

03 / Academic

Training, teaching & service

A short record of my academic path and work with the probability community.

Education

2022–2026Ph.D. in Probability Theory and Mathematical Finance

Shanghai University of Finance and Economics

2019–2022M.Phil. in Probability Theory and Mathematical Finance

Shanghai University of Finance and Economics

2013–2017B.S. in Mathematics and Applied Mathematics

Shanghai University

Teaching & talks

2019–2023 · Teaching assistantShanghai University of Finance and Economics

Linear algebra, calculus, probability theory, stochastic processes, and graduate probability and stochastic processes.

November 2024 · SpeakerNational Mathematics Frontier Doctoral Academic Exchange Forum

Peking University · Probability, Statistics, and Financial Mathematics session.

Professional service

  • Reviewer for Bernoulli
  • Statistics & Probability Letters
  • Probability in the Engineering and Informational Sciences
  • Methodology and Computing in Applied Probability
  • Journal of Mathematical Analysis and Applications
Contact

Let’s talk about probability.